Understanding Your Paycheck and Finances
Why take-home pay differs from your salary: taxes, benefits and other deductions explained, and how to budget from what actually arrives...
Reviewed by Marco Moreno, Underwriter & Operations Manager · October 2026
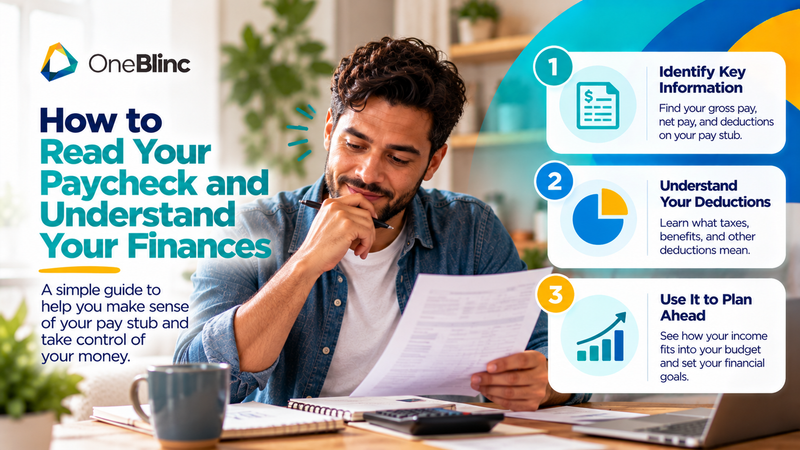
Your take-home pay is often different from the salary or hourly rate you expect. Understanding the numbers on a pay stub makes it easier to budget, spot errors, and plan for irregular income.
Gross pay versus net pay
Gross pay is earnings before deductions. Net pay is what remains after applicable taxes, benefit contributions, and other withholdings. Use net pay for your everyday spending plan.
Read common deductions
Pay stubs may include federal and state taxes where applicable, Social Security, Medicare, insurance, and retirement contributions. Exact items depend on your job and location.
Check hours and rates
For hourly work, compare hours, overtime, and pay rates with your records. For salaried work, review pay-period amounts and any adjustments.
Understand pay frequency
Weekly, biweekly, twice-monthly, and monthly schedules create different cash-flow patterns. Biweekly pay generally means 26 paychecks in a full year, while twice-monthly means 24.
Build a paycheck-based spending plan
Start with dependable net income and the bills due before the next payday. For variable earnings, use a conservative baseline and decide in advance how to handle higher-pay periods.
A practical example
If gross pay is $1,500 but net pay is $1,180, a budget based on $1,500 will overstate available cash by $320 for that paycheck. Build the plan around the amount actually deposited.
Pay stub review checklist
Compare gross pay with your hours worked or salary.
Review each deduction: taxes, benefits, and retirement contributions.
Confirm that net pay matches the amount deposited.
Report any discrepancy to payroll promptly.
Pre-tax vs. post-tax deductions
Not all deductions affect your paycheck the same way. Pre-tax deductions, such as many employer health insurance premiums and traditional 401(k) contributions, are taken out before income taxes are calculated. That can lower your taxable income. Post-tax deductions, such as Roth retirement contributions or certain voluntary benefits, come out after taxes. Knowing the difference helps you understand why increasing a retirement contribution may reduce your take-home pay by less than the amount you contribute.
How to read your W-4 and withholding
The federal income tax withheld from each paycheck is based on the information you provide on Form W-4. If too little is withheld, you may owe money at tax time. If too much is withheld, you may receive a refund but have less money in each paycheck during the year. Life changes such as marriage, a new child, or a second job can affect the right amount. The IRS offers a Tax Withholding Estimator on its website to help you review your situation.
Understand the pay stub abbreviations
YTD: year-to-date totals for earnings and deductions.
FICA: Social Security and Medicare taxes.
FIT or FWT: federal income tax withheld.
SIT: state income tax, where applicable.
Plan around your pay frequency
A paycheck that arrives every two weeks behaves differently from one paid twice a month. With biweekly pay, two months each year typically include a third paycheck, which can be used to catch up on savings or irregular expenses. With twice-monthly pay, each check arrives on a predictable date, which can make matching bills easier. Weekly pay offers smaller, more frequent deposits, which can help with cash flow but requires careful planning for larger monthly bills like rent.
Keep records organized
Save your pay stubs, especially the final one of each year, until you have filed your taxes and confirmed your W-2 matches. These records can also help when applying for loans, apartments, or assistance programs.
Related OneBlinc guides
Explore OneBlinc
If a paycheck timing gap is part of your situation, download OneBlinc to explore BlincAdvance™ and check current eligibility and terms. OneBlinc offers a subscription service starting at $8.99 per month, a free standard deposit option, and an optional instant deposit for an additional fee. Available advance amounts depend on eligibility and applicable terms. Only use an advance when you have a clear repayment plan.
Educational content only; not individualized financial, legal, tax, or medical advice. Eligibility rules apply.
Frequently Asked Questions
Why did my take-home pay change?
Possible reasons include different hours, tax withholding, benefits, bonuses, or payroll adjustments. Ask payroll if an item is unclear.
Where can I find year-to-date totals?
Many pay stubs include year-to-date earnings and deductions, which help with financial planning and recordkeeping.
What should I do if I find an error on my paycheck?
Contact your payroll or HR department promptly and bring your pay stub and records of the hours you worked.
OneBlinc Editorial Team
The OneBlinc Editorial Team writes practical guides on budgeting, paychecks, saving, and handling financial emergencies. Every article is researched, edited for accuracy, and updated when rules or products change. Our content is educational and is not individualized financial advice.
OneBlinc Blog
OneBlinc helps eligible workers manage paycheck timing with BlincAdvance™. Eligibility and terms apply.
Visit SiteDon't miss an update!
Subscribe to get our fresh news!