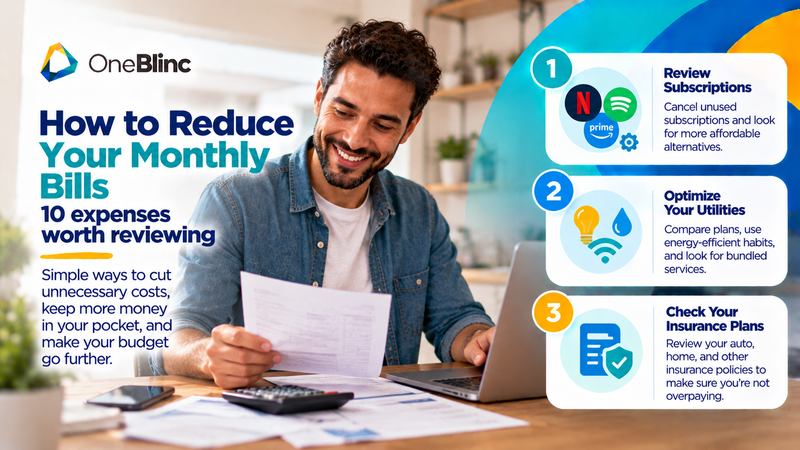
How to Reduce Your Monthly Bills: 10 Expenses Worth Reviewing
Ten recurring bills worth reviewing, from insurance and subscriptions to phone and internet, with tips on what to ask providers...
Reviewed by Gil Hackl, Fintech Builder & Operator · October 2026
Recurring bills can quietly consume a large share of take-home pay. A monthly expense audit can reveal savings without requiring major lifestyle changes. Start with the charges that repeat automatically.
1–2. Streaming and app subscriptions
Review services such as Netflix and other streaming or app memberships. Cancel unused plans, rotate services instead of keeping them all active, and compare ad-supported or family options where permitted.
3–4. Phone and internet
Compare current plans with actual data usage and local alternatives. Ask your provider about available discounts, promotional expirations, and lower-cost tiers.
5–6. Insurance and banking fees
Compare insurance quotes with equivalent coverage and deductibles. Review checking-account maintenance fees, overdraft settings, and ways to qualify for fee waivers.
7–8. Utilities and energy use
Check for billing errors, budget-billing programs, and energy-saving changes that fit your home. Small usage adjustments can help, but avoid compromising safety or health.
9. Transportation-related memberships
Review parking plans, roadside assistance, transit passes, and other recurring transportation charges. Check whether benefits overlap with coverage you already have.
10. Debt and payment-plan costs
Review interest charges, due dates, and available hardship or refinancing options. Compare the full cost and terms before changing an obligation.
Turn savings into a buffer
Redirect a portion of recurring savings to an emergency fund. Confirm that canceled subscriptions no longer appear on the following statement.
A practical example
If you cancel two unused subscriptions costing $9 and $13 per month, the potential savings are $22 monthly or $264 over a year, assuming the prices stay the same.
Monthly bill audit checklist
List every recurring charge from your bank and card statements.
Cancel or pause services you have not used in the past month.
Call phone, internet, and insurance providers to ask about lower-cost options.
Confirm canceled charges no longer appear on the next statement.
How to negotiate a lower bill
Many recurring bills have more flexibility than their advertised rates suggest, especially for long-time customers. A short, polite call can sometimes produce real savings.
Before you call
Look up what new customers are currently being offered.
Note how long you have been a customer and your payment history.
Check what competitors charge for similar service in your area.
During the call
Explain that you are reviewing your budget and ask whether there are any promotions, loyalty discounts, or lower-cost plans available. If the first representative cannot help, ask whether the retention or customer loyalty department can review your account. Be honest about whether you would actually switch. Confirm any new rate, the length of the promotion, and whether a contract is required.
Watch for price creep
Bills often rise slowly. A promotional rate expires, a small fee is added, or a service quietly increases by a few dollars. Each change may seem minor, but together they can add up over a year. Set a calendar reminder for when promotions end, and compare each month's statement against the last. If a charge increases without explanation, ask the provider what changed.
Bundle or unbundle thoughtfully
Bundling internet, phone, and TV can reduce costs, but only if you use every service in the bundle. Sometimes separating services and dropping the ones you rarely use is cheaper. Compare the total cost of each option, including equipment rental fees and taxes.
A simple bill-cutting example
Imagine lowering your internet bill by $15 a month, switching to a cheaper phone plan to save $20, and canceling a $12 streaming service you rarely watch. Together, that is $47 a month, or $564 over a year, money that could go toward an emergency fund or paying down debt.
Related OneBlinc guides
Explore OneBlinc
If a paycheck timing gap is part of your situation, download OneBlinc to explore BlincAdvance™ and check current eligibility and terms. OneBlinc offers a subscription service starting at $8.99 per month, a free standard deposit option, and an optional instant deposit for an additional fee. Available advance amounts depend on eligibility and applicable terms. Only use an advance when you have a clear repayment plan.
Educational content only; not individualized financial, legal, tax, or medical advice. Eligibility rules apply.
Frequently Asked Questions
How often should I audit recurring bills?
A quarterly review is a useful habit, with an additional check when promotions expire or household needs change.
Is it worth calling providers to ask for a lower rate?
Often it is. Providers may offer retention discounts, cheaper plans, or current promotions, though results vary.
Which monthly bill is usually easiest to lower first?
Subscriptions and services you no longer use are often the quickest wins, followed by phone and internet plans.
OneBlinc Editorial Team
The OneBlinc Editorial Team writes practical guides on budgeting, paychecks, saving, and handling financial emergencies. Every article is researched, edited for accuracy, and updated when rules or products change. Our content is educational and is not individualized financial advice.
OneBlinc Blog
OneBlinc helps eligible workers manage paycheck timing with BlincAdvance™. Eligibility and terms apply.
Visit SiteDon't miss an update!
Subscribe to get our fresh news!