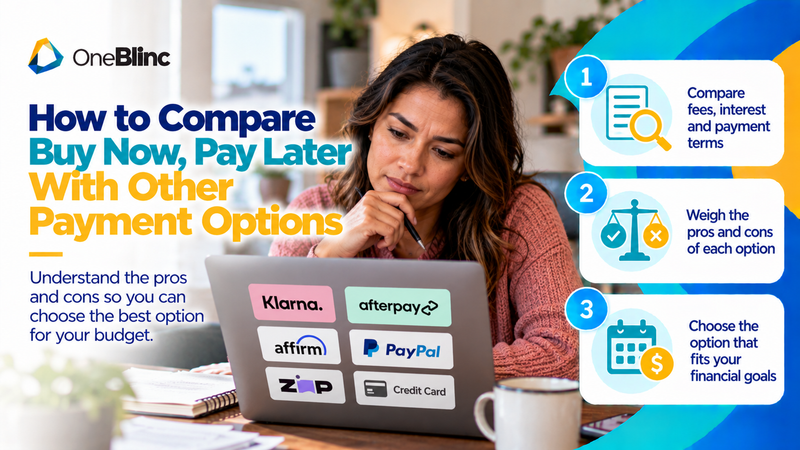
How to Compare Buy Now, Pay Later With Other Payment Options
Compare buy now, pay later with cards and saving first: map every installment, check fees and returns, and avoid stacking plans...
Reviewed by Marco Moreno, Underwriter & Operations Manager · October 2026
Buy now, pay later plans can make a purchase appear affordable by splitting its price. The important question is whether the full obligation fits your upcoming budget.
Map every installment
Write down each payment date and amount, including any existing plans. Several small payments can overlap unexpectedly.
Read fees and consequences
Some plans charge late fees or other costs, and missed payments may have consequences. Terms vary by provider and product.
Check returns and disputes
Understand how refunds work when an item is returned and whether payments continue while a dispute is reviewed.
Compare with saving first
For nonessential purchases, waiting and saving may avoid repayment pressure. For essential expenses, compare all available alternatives.
Protect next-paycheck cash flow
Include installments in your paycheck budget before making a new purchase.
How buy now, pay later typically works
Buy now, pay later, often shortened to BNPL, lets you split a purchase into several payments. A common structure is four equal installments, with the first due at checkout and the rest every two weeks. Other plans stretch payments over several months and may charge interest. Approval decisions are usually made quickly at checkout, and providers may review information such as your payment history with them or other data. Because each provider sets its own terms, two plans that look similar at checkout can have very different costs if a payment is missed.
BNPL compared with other payment options
Debit card or cash
Paying in full avoids debt and fees entirely, but requires having the money available now.
Credit card
A credit card offers flexibility and consumer protections. If you pay the statement balance in full each month, you may avoid interest. Carrying a balance, however, can become expensive because of ongoing interest charges.
Store financing
Some retailers offer promotional financing for larger purchases. Watch for deferred interest offers, where interest can be charged on the full original amount if the balance is not paid off by the end of the promotion.
Saving first
For purchases that can wait, saving over a few weeks avoids repayment pressure and gives you time to decide whether you still want the item.
The risk of stacking plans
One BNPL plan may feel easy to manage, but several at once can quietly add up. Because payments come from different providers on different dates, it can be hard to see the total you owe. Before using a new plan, list every active installment, its amount, and its due date. Add up what is due over the next two paychecks. If the total would squeeze rent, groceries, or other essentials, it is a sign to pause new purchases.
Questions to ask before you click buy
Would I buy this today if I had to pay the full price upfront?
What happens if a payment fails or is late?
Is the first payment and every future payment covered in my budget?
How do returns work, and will payments pause during a dispute?
Am I using BNPL for a necessity because my budget is already stretched?
If the last answer is yes, it may be worth exploring other options, such as a payment plan with the provider or local assistance, before adding new installment payments.
Example: two plans at once
Say you buy $200 headphones and a $320 appliance with two separate pay-in-four plans. After the first payments at checkout, you owe $50 and $80 every two weeks, or $130 per pay period for about six weeks. That may be manageable, or it may collide with rent. Writing out the schedule before buying shows the real impact on each paycheck.
Related OneBlinc guides
Explore OneBlinc
If a paycheck timing gap is part of your situation, download OneBlinc to explore BlincAdvance™ and check current eligibility and terms. OneBlinc offers a subscription service starting at $8.99 per month, a free standard deposit option, and an optional instant deposit for an additional fee. Available advance amounts depend on eligibility and applicable terms. Only use an advance when you have a clear repayment plan.
Educational content only; not individualized financial, legal, tax, or medical advice. Eligibility rules apply.
Frequently Asked Questions
Is buy now, pay later interest-free?
Some plans are, but not all. Read the specific agreement.
Can missed payments affect credit?
Consequences vary by provider and reporting practices; check current disclosures.
Can I pay off a buy now, pay later plan early?
Many plans allow early payoff, but check the provider's terms for any conditions before you pay.
OneBlinc Editorial Team
The OneBlinc Editorial Team writes practical guides on budgeting, paychecks, saving, and handling financial emergencies. Every article is researched, edited for accuracy, and updated when rules or products change. Our content is educational and is not individualized financial advice.
OneBlinc Blog
OneBlinc helps eligible workers manage paycheck timing with BlincAdvance™. Eligibility and terms apply.
Visit SiteDon't miss an update!
Subscribe to get our fresh news!