How Much Does a Cash Advance Cost?
How to calculate the real cost of a cash advance: subscription fees, instant transfer charges and how often you use it, with a worked example...
Reviewed by Gil Hackl, Fintech Builder & Operator · October 2026
The cost of a cash advance is not always captured by a single number. To compare services fairly, identify every fee you might pay and how often you expect to use the product.
Identify subscription charges
Some apps charge a monthly membership whether or not you request an advance. A small monthly amount becomes a meaningful annual cost when multiplied by twelve.
Separate standard and faster transfers
A standard deposit may be free while an optional instant or expedited transfer costs extra. Check the fee displayed before choosing a delivery method and allow for processing times.
Look for other charges
Depending on the provider, there may be transaction fees or other terms that affect the overall cost. Read the pricing and repayment disclosures before authorizing an advance.
Calculate cost for your actual use
Add membership charges attributable to your usage and any optional transfer fees. Compare that total with a payment extension, an employer benefit, or other available alternatives.
Consider the cost of repayment
Even a low-fee advance reduces cash available after repayment. If you need another advance immediately afterward, that is a signal to reassess the underlying budget gap.
A practical example
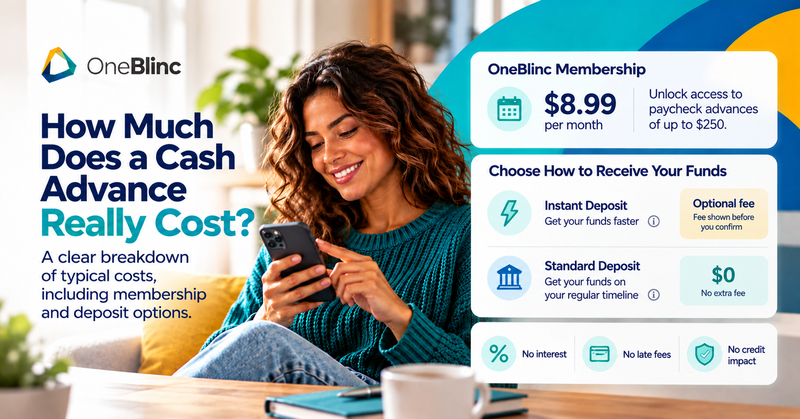
OneBlinc offers BlincAdvance™ through an $8.99 monthly subscription, with a free standard deposit option and an optional instant deposit for an additional fee. Check the current in-app terms and eligibility before deciding whether it fits your situation.
Cash advance cost checklist
List every possible charge: membership, standard transfer, and instant transfer.
Estimate your monthly cost based on how often you expect to use the service.
Compare that total with low-cost alternatives such as a bill extension.
Recheck the in-app pricing before each request, since terms can change.
Why APR can be confusing for short-term advances
Annual percentage rate, or APR, is designed to compare the yearly cost of borrowing. When a fee is charged on a very short-term product, converting it to an annual rate can produce a number that looks very high, even if the dollar cost is small. For example, a small fee on an advance repaid within two weeks would translate into a large annualized figure. That is why it helps to look at both: the APR, if disclosed, for comparison, and the actual dollar amount you will pay. Neither number alone tells the whole story.
Hidden costs to watch for
Beyond the main fees, some costs are easy to overlook when comparing cash advance options.
Optional tips: some services suggest a tip. Understand whether it is truly optional and how it affects your total cost.
Overdraft risk at repayment: if repayment is withdrawn when your balance is low, your bank may charge its own fees.
Recurring memberships: a monthly fee continues even in months you do not use the service, unless you cancel.
Faster transfer fees: paying for speed each time can add up quickly if it becomes a habit.
Compare with other short-term options
Before choosing any advance, compare it with alternatives. A biller may offer a payment extension at no cost. An employer may offer earned wage access or a payroll advance. A credit union may offer a small-dollar loan with clear terms. A credit card cash advance often carries its own fee and interest that may begin immediately. Writing down the total dollar cost of each option for your specific amount and timeline makes the comparison much clearer.
A simple cost worksheet
List the amount you need, the date you need it, and when you can repay. Next to each option, write the fees, how repayment works, and the total you will pay. The option with the lowest total cost that fits your timeline is often the strongest choice.
Related OneBlinc guides
Explore OneBlinc
If a paycheck timing gap is part of your situation, download OneBlinc to explore BlincAdvance™ and check current eligibility and terms. OneBlinc offers a subscription service starting at $8.99 per month, a free standard deposit option, and an optional instant deposit for an additional fee. Available advance amounts depend on eligibility and applicable terms. Only use an advance when you have a clear repayment plan.
Educational content only; not individualized financial, legal, tax, or medical advice. Eligibility rules apply.
Frequently Asked Questions
Does a free standard deposit mean the entire service is free?
No. A service can offer a free standard transfer while charging a subscription or other optional fees.
What is the best way to compare costs?
Use the total dollars you would actually pay over a month or year, including optional expedited transfers.
How can I keep the cost of a cash advance down?
Choose the standard deposit when timing allows, request only what you need, and cancel subscriptions you no longer use.
OneBlinc Editorial Team
The OneBlinc Editorial Team writes practical guides on budgeting, paychecks, saving, and handling financial emergencies. Every article is researched, edited for accuracy, and updated when rules or products change. Our content is educational and is not individualized financial advice.
OneBlinc Blog
OneBlinc helps eligible workers manage paycheck timing with BlincAdvance™. Eligibility and terms apply.
Visit SiteDon't miss an update!
Subscribe to get our fresh news!